
Banker turned broker
Our reputation isn't built on how many loans we close.
It's built on how many we close that other lenders couldn't.
We don't have to make your loan fit one bank's box.
- We shop 175+ lenders for the right combination of price, program, and approval.
- If one lender says no, we keep looking.
- That's how we say yes more often than we say no.
- No documents to start
- No credit pull
- No obligation
Brian Poetschlag
Mortgage Broker · West Capital Lending, Inc.
- Since 2002
- 32 states
- 175+ lenders
Loans for people a bank says no to
Self-employed, an investor, on a W-2, or sitting on equity you cannot reach. Every one of these is a loan I write, and most of them a bank will not.


What is your home worth right now?
One ZIP code. Typical value where you live and what it has done over the last twelve months, across 26,000+ ZIP codes. No email, no sign-up.
Zillow Home Value Index, all homes, smoothed and seasonally adjusted. A typical value for the middle of the market, not an appraisal and not a valuation of your home.
There is almost always an option
Twenty-four years in this business, and from 2007 to 2024 I was on the retail banking side. A lot of that job was fighting to get self-employed borrowers approved, and losing, because the bank had one box and they did not fit it. A denial feels final, but it is one institution applying one rulebook.
A bank has one product. If your file does not fit it you hear “no”, and it sounds like the end of the road. Nobody tells you it was one institution applying one rulebook.
Almost every homeowner who calls me has at least one option on the table. Not always the one they expected, and not always one they want to take — but an option.
- HELOC
- Home equity loan
- Cash-out refinance
- Home equity agreement
- Reverse mortgage
- Bank statement
- DSCR
- Private money
- Bridge
- Temporary buydown
Which one you take, or whether you take any of them, is your decision. My job is to put the real choices in front of you with the numbers attached. If the deal you already have wins, I will say so.
Your free home equity report
What it is worth, what you owe, what is yours, and where the gain actually came from. The same kind of report the big platforms charge lenders for.
- What your home is worth, and the twelve-month trend
- What you owe, and how much of the equity you can actually reach
- Where the gain came from — the market, or your own payments
- What a little extra each month would save you
Free. No email, no sign-up, no credit pull.
Where do you want to start?
Pick the one that sounds like you. No form in the way.
Or work out a number first
Get a free rate quote.
No application. No credit pull. A written comparison across 175+ lenders, with the APR on each.
What clients say
Brian was fantastic! He listened to us, took in everything he heard and followed it up with options that not only worked for us, but also far exceeded our expectations.
Great person to deal with for business; you understand and put no pressure. He talk like he knew me for years and he was honest.
This was a great experienc. Brian was very helpful and helped us through the entire process.
Quoted word for word from my Experience.com profile (5.0 stars from 8 reviews).
Know the questions before you make the call
Know the questions before you talk to anyone. Start with these.
Free: The Home Loan Navigator
My book, in plain English. What lenders actually check, how to read a Loan Estimate, and the mistakes that cost the most. No email required.
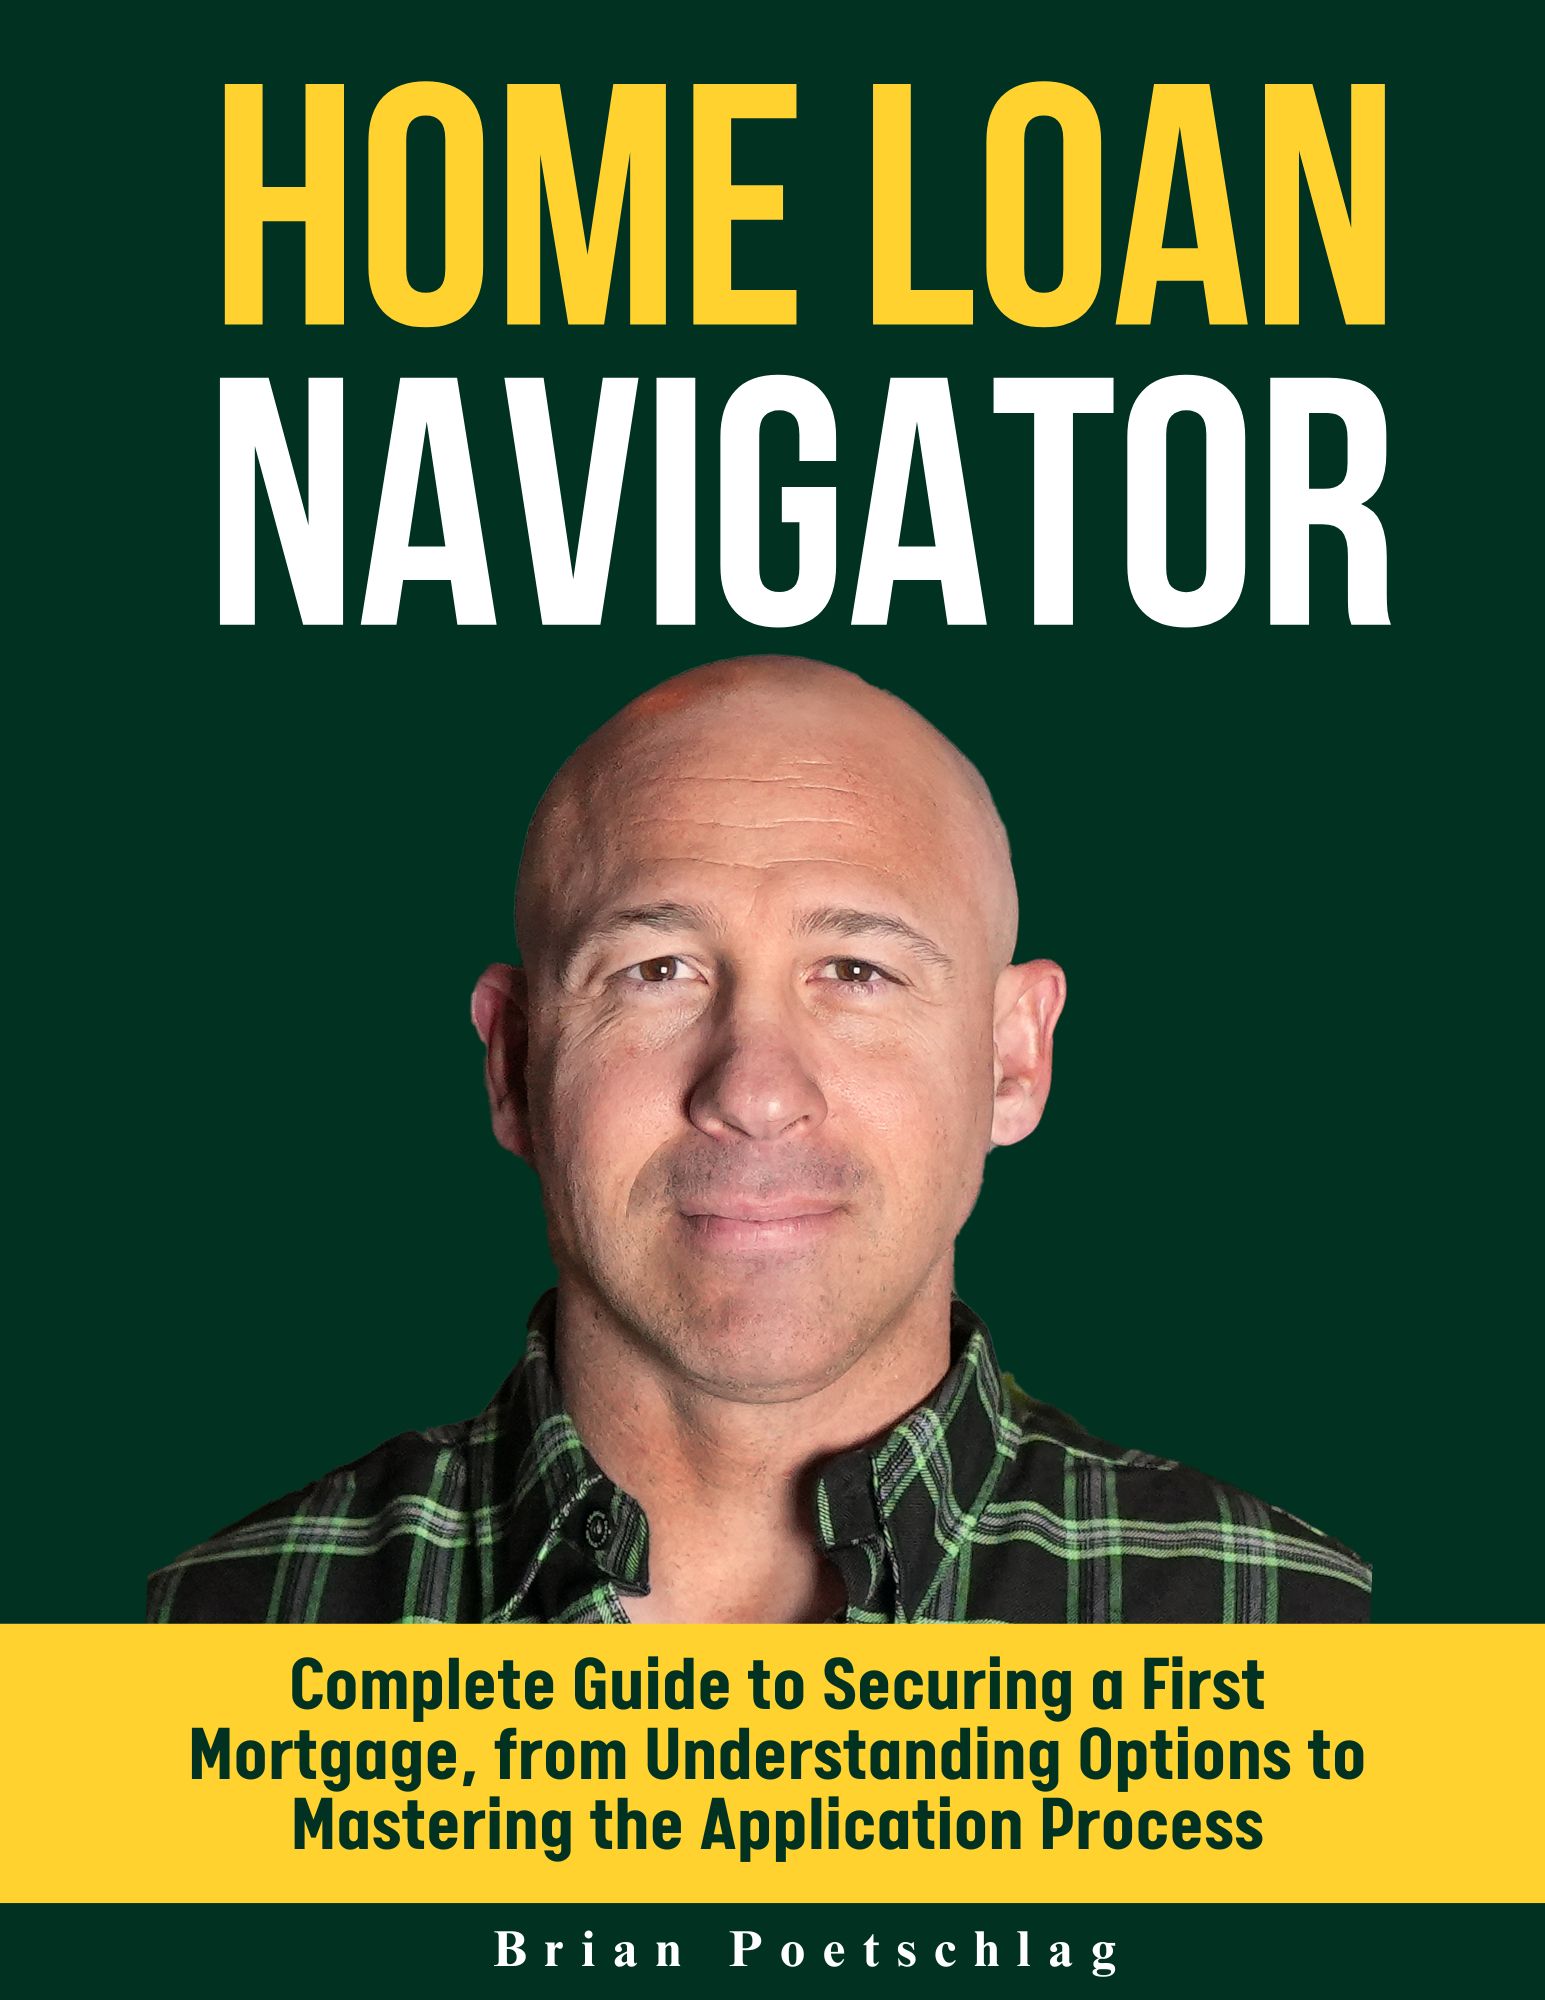
The Home Loan Navigator
Everything I wish borrowers knew before they called a lender. What underwriters actually check, how to read a Loan Estimate line by line, the add-backs most banks never apply, and the mistakes that cost the most money.
No email required. No form. Just the book.
Ready when you are
A written comparison across 175+ lenders
Not a rate on a screen. A document you can hold next to your bank’s offer and see which one is really cheaper.
- Every program that fits you, side by side — not just the one I earn most on
- Real fees, itemised, and the APR on each so the comparison is honest
- A straight answer. If the deal you already have wins, that is what the document says
- Takes about a minute
- No credit pull
- No application
Questions people ask
Will this hurt my credit score?
Not to start. The Equity Snapshot on this page pulls nothing. The West Capital Lending Digital HELOC uses a soft pull to show you an offer, which doesn't affect your score. A hard pull only happens when you choose to move forward on a specific loan, and you'll know before it happens.
Do I have to give up my 3% first mortgage?
No. A HELOC is a second lien, so your first mortgage stays exactly where it is. A cash-out refinance replaces it, and sometimes that still wins on the math. I'll put both side by side and let the numbers decide.
What does it cost to talk to you?
Nothing. I'm paid when a loan closes, and the compensation is disclosed on your Loan Estimate. If the best answer is to keep what you have, you'll hear that, and it cost you fifteen minutes.
I'm self-employed. Is that a problem?
At a bank, often. Here it's a Tuesday. Bank-statement and P&L programs use your deposits instead of your tax returns, and DSCR loans qualify investment property on its rent.
How fast can this close?
The West Capital Lending Digital HELOC can fund in as little as 5 days when the closing is done online. Purchases and refinances run on normal timelines, and I give you a real date at the start instead of a hopeful one.
What states are you licensed in?
32 states. The full list, with my NMLS and California DRE numbers, is on the licensing page. Call or text with your state and I'll confirm in one message.
Let’s look at your numbers
Fifteen minutes. Your real numbers. No pressure.
Call or text my cell, or book a time. You’ll get a written comparison with real terms and an APR on every option, and if your current deal already wins, I’ll tell you.